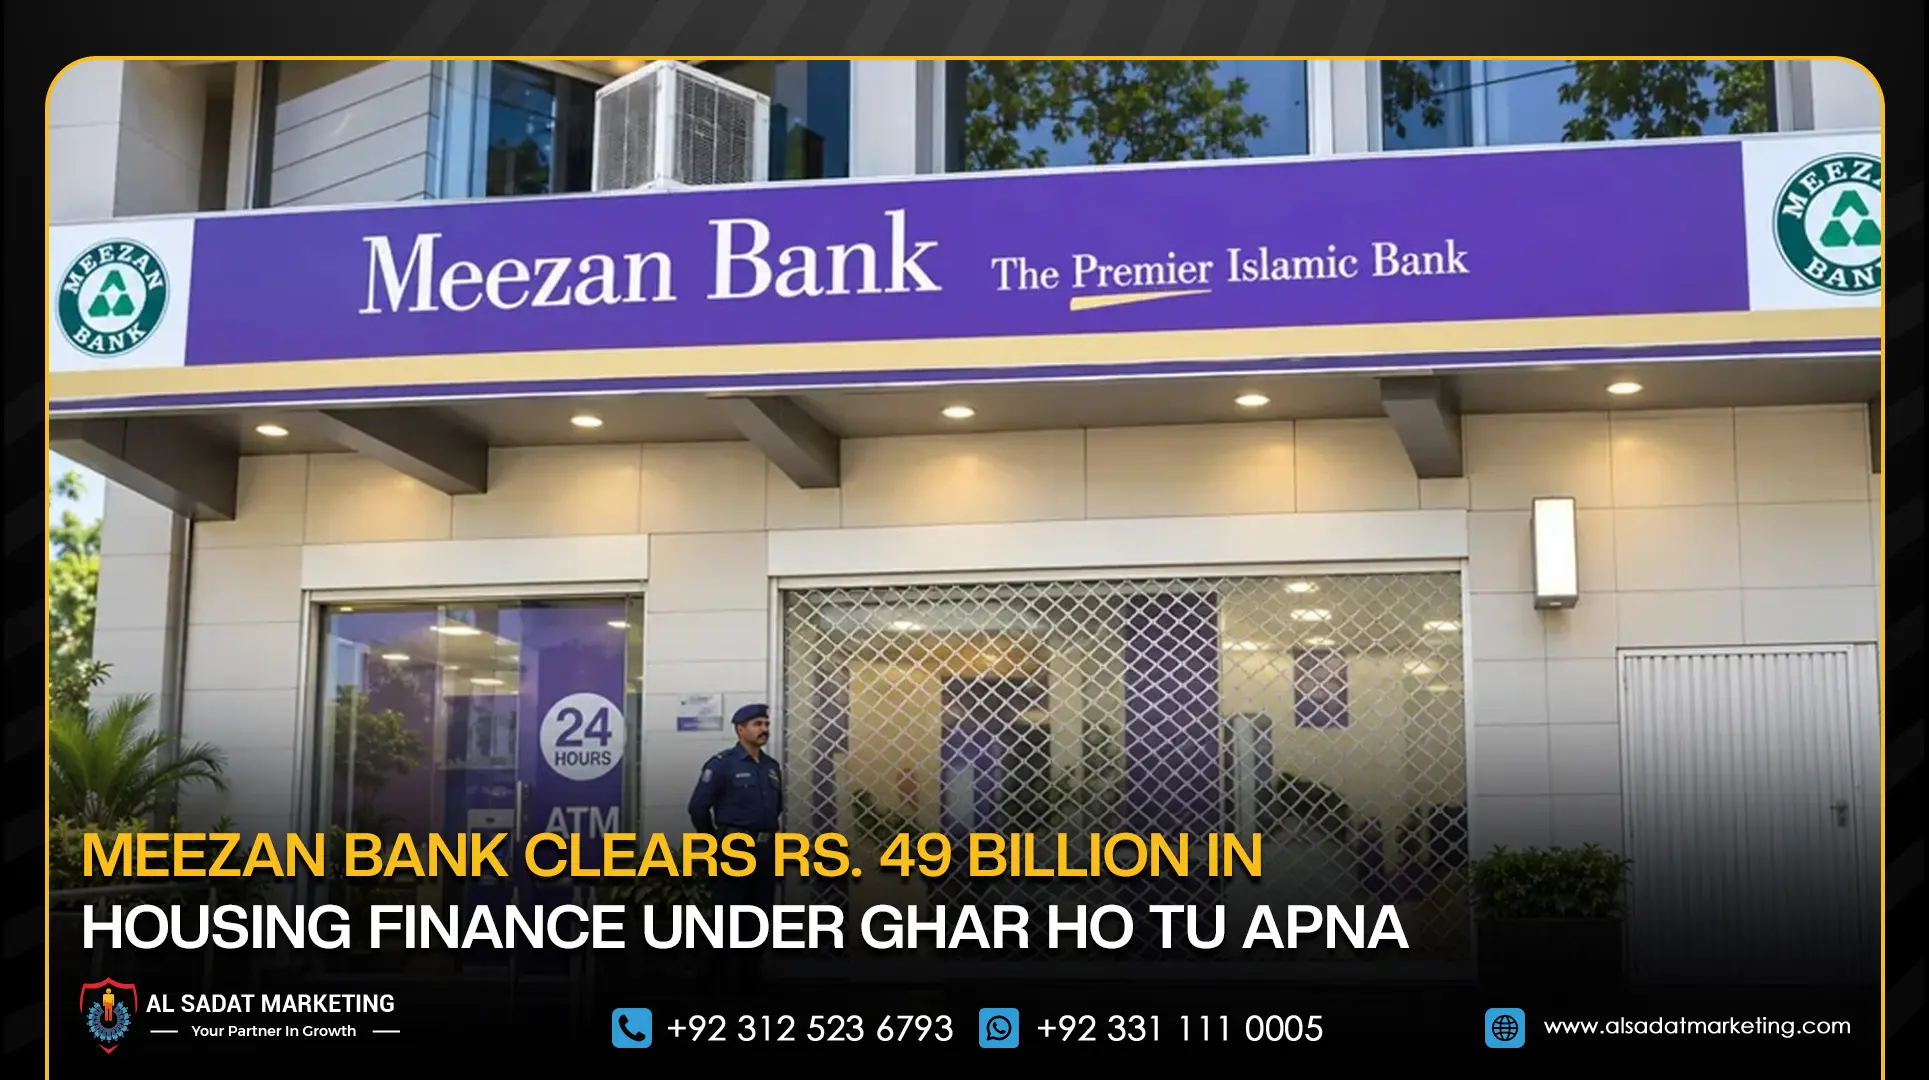
KARACHI: Meezan Bank has approved housing finance applications worth approximately Rs. 49 billion under the government’s Ghar Ho Tu Apna (GHTA) programme, according to the bank’s reported figures. The initiative aims to make homeownership more accessible by providing subsidised financing to eligible applicants.
The bank has received more than 27,800 applications seeking financing of around Rs. 179 billion. Of these, 6,880 applications, valued at approximately Rs. 49 billion, have been approved.
However, the amount reaching beneficiaries remains considerably lower than the total approved financing. As of September 30, 2026, around 1,000 families had received financing totalling Rs. 7.34 billion.
Applications Exceed Rs. 179 Billion
The volume of applications indicates substantial interest in the government-backed housing finance programme. Applicants have sought financing across more than 27,800 cases, while the bank has approved 6,880 applications.
Based on the reported figures, approvals account for roughly one-quarter of applications by number. The available information does not clarify the status of all remaining applications, which may include cases awaiting review or those that were not approved.
The figures relate specifically to Meezan Bank’s participation in Ghar Ho Tu Apna. They should not be interpreted as the programme’s nationwide application, approval or disbursement totals.
Disbursements Remain Below Approved Financing
Although the bank has approved financing worth Rs. 49 billion, the reported disbursements stood at Rs. 7.34 billion by September 30, 2026. This amount had reached 1,000 families.
The difference highlights an important distinction between approving a housing loan and releasing the funds. Applicants may still need to complete documentation and other financing requirements before receiving their money, although the bank’s figures do not specify the reasons for the gap in these cases.
Actual disbursements are particularly important for the housing market because they determine when eligible buyers can proceed with property purchases or other permitted housing expenses.

Implications for Homebuyers and the Property Market
The programme could support demand for affordable housing by helping eligible households access financing. However, its practical impact will depend partly on how efficiently approved cases progress to disbursement and completed housing transactions.
Applicants should contact their bank for updates on application status, outstanding documents and the conditions required before funds can be released. Property developers and sellers should also distinguish between financing approvals and money actually received by buyers when assessing demand.
Meezan Bank’s reported figures offer a snapshot of its role in the programme, rather than a complete picture of housing finance across Pakistan. Further disclosures on disbursements and the status of pending applications will help show how quickly approved financing is translating into homeownership.
Applicants can consult the State Bank of Pakistan and the Ministry of Finance for official information about the wider housing finance programme and its implementation.