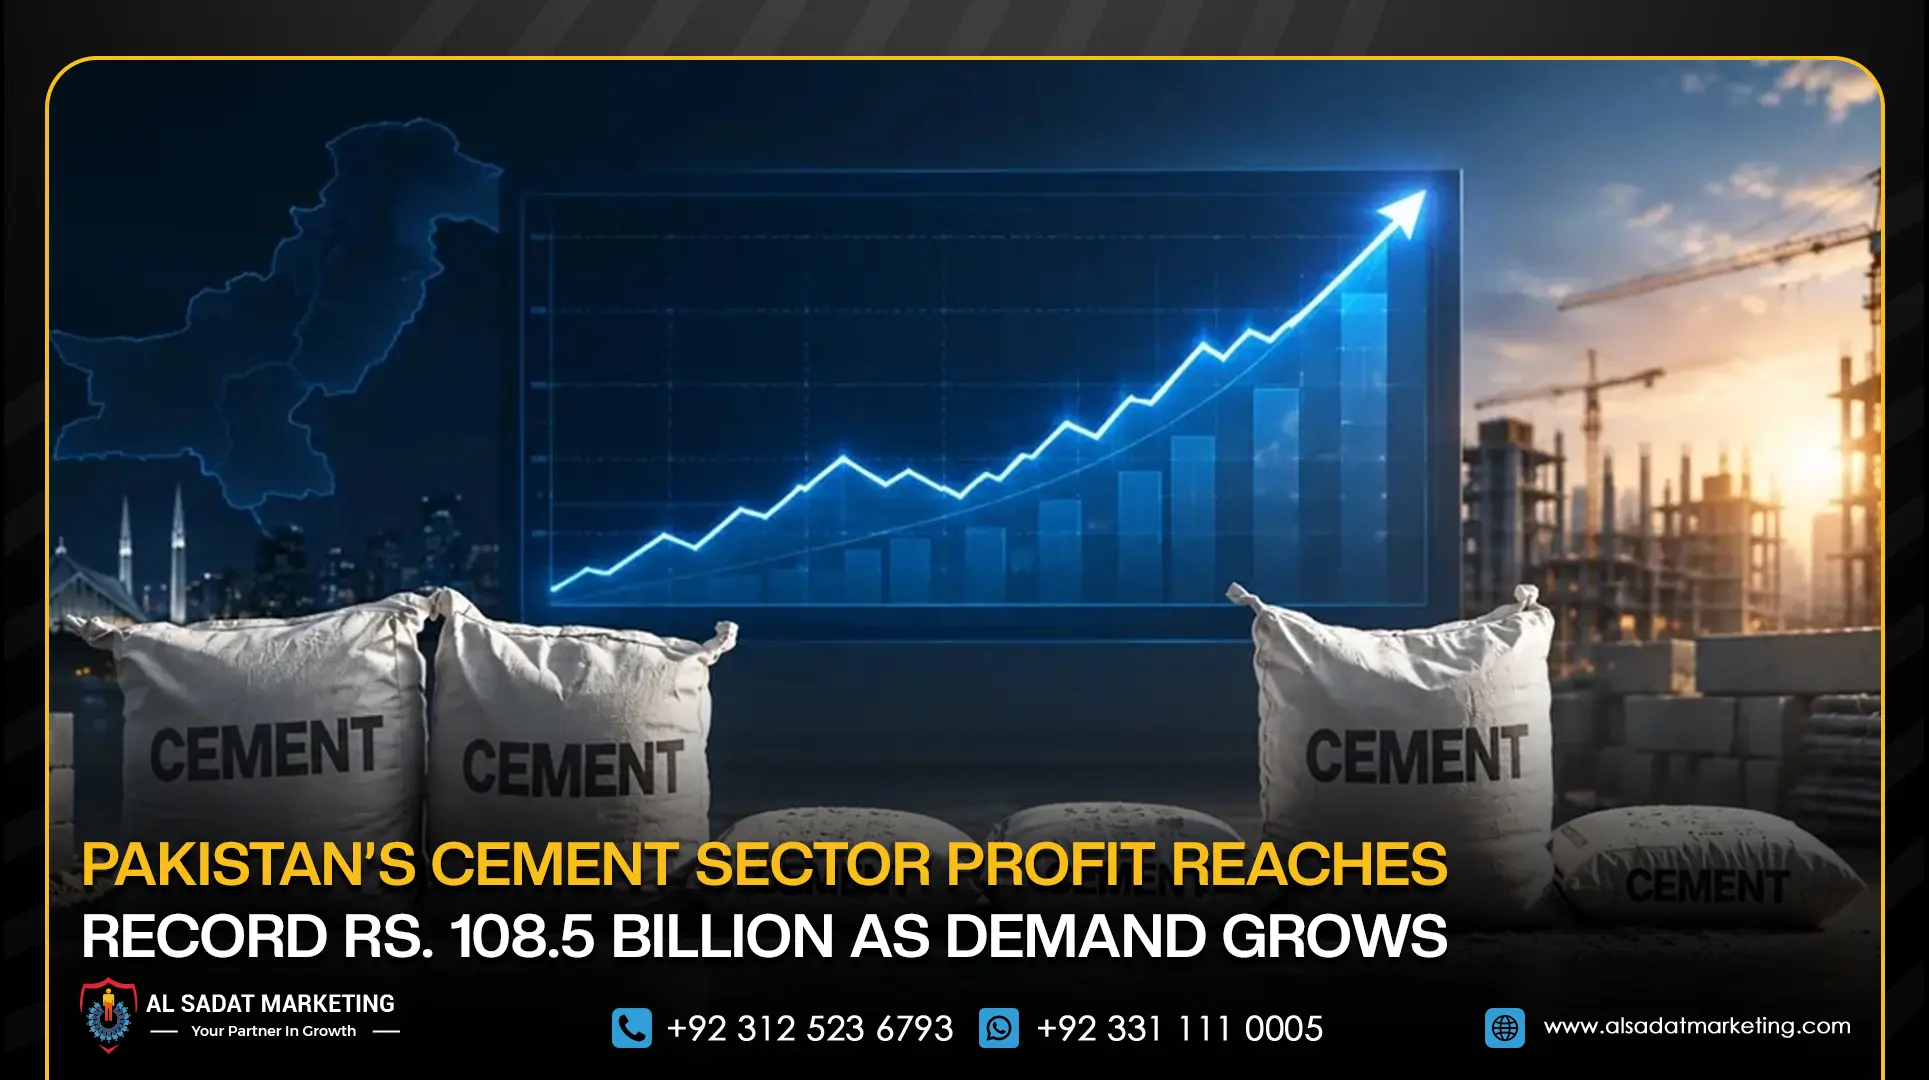
ISLAMABAD: Pakistan’s listed cement companies recorded a combined net profit of Rs. 108.5 billion during FY2025-26, marking an 18% increase from Rs. 91.73 billion in the previous financial year and taking annual sector earnings above the Rs. 100 billion threshold for the first time.
The improvement came alongside stronger cement demand, with combined offtake among the companies covered rising 5% to 32.28 million tonnes from 30.78 million tonnes a year earlier.
Combined sales also increased 7% to Rs. 494.2 billion compared with Rs. 462.67 billion in FY2024-25.
Higher Cement Demand Supports Earnings
The increase in cement consumption provides an important indicator of stronger activity across the construction sector.
The companies recorded higher volumes during the year, while improved selling prices also contributed to the increase in revenue. Gross profit rose 7% to Rs. 169.09 billion, with the combined gross margin edging up to 34.2% from 34.0%.
The improvement remained relatively moderate at the margin level, however, as higher coal and transportation costs continued to put pressure on production and distribution expenses.
Other Income Adds to Sector Profitability
Cement producers also benefited from stronger income outside their core cement operations.
Other income increased by around 20% during the year, while companies expanded their cash and short-term investment holdings by approximately 37%.
The increase in these financial holdings provided an additional contribution to overall earnings alongside revenue generated from cement sales.
Lucky Cement Posts Strong Results
Lucky Cement was among the major contributors to the sector’s performance, reporting annual earnings of more than Rs. 96 billion.
The company has significant production capacity across its facilities in Pezu, Nooriabad and Jamshoro. Its domestic cement volumes increased 11% during FY2025-26 to approximately 6.52 million tonnes.
The company’s stronger domestic volume growth exceeded the overall 5% increase recorded across the covered cement companies.
Lower Financing Costs Provide Additional Support
Reduced finance costs were another factor supporting profitability during the year.
The decline in Pakistan’s interest-rate environment from the highs recorded during the previous monetary tightening cycle helped reduce borrowing expenses for companies with debt linked to their operations and production capacity.
For the cement industry, financing costs remain an important consideration because large-scale manufacturing facilities require significant capital investment and working capital.
Input Costs Remain a Challenge
Despite the record profit figure, cost pressures remain a key concern for cement producers.
Coal is a major input in cement manufacturing, while transportation expenses also affect the cost of moving raw materials and finished cement. Increases in these expenses limited the extent to which the sector could improve its gross margins despite higher volumes and sales.
Future movements in energy, fuel and transportation costs could therefore influence the industry’s profitability.
What the Results Indicate for Construction Activity
The 5% increase in cement offtake provides a positive indication for construction activity across Pakistan.
Cement consumption is closely linked to physical construction work, including residential development, commercial projects and infrastructure activity. The increase therefore offers a useful measure of construction-sector momentum beyond project announcements or planned investments.
Higher cement sales also suggest that improved activity was translating into actual demand for construction materials during the financial year.
Implications for Property and Development
The cement sector’s record earnings and increased offtake provide a positive signal for Pakistan’s broader construction and property markets.
Developers, contractors and investors can view stronger cement consumption as evidence of improving building activity, although sector profitability should not be treated as a direct indicator of property prices.
Going forward, the sustainability of this momentum will depend on several factors, including interest rates, construction demand, energy costs, coal prices and transportation expenses.
The latest results show that Pakistan’s cement industry entered FY2025-26 with stronger volumes and profitability, but maintaining that performance will depend on how effectively companies manage rising input costs and changing financing conditions.